EasyBudget - Budget planning
Wallet Passes Alliance
- 4.0
- 2.55K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
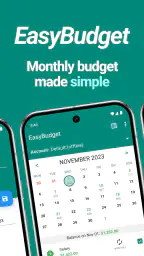
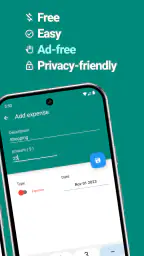
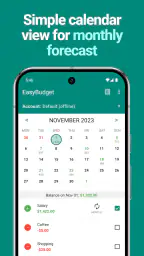
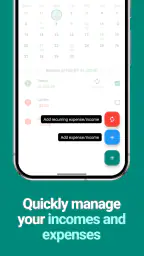
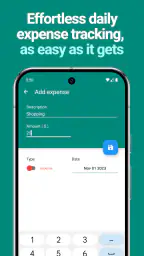
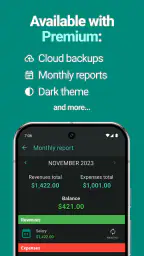
EasyBudget - Budget planning Pros and Cons
Pros
- Simple interface makes daily expense tracking quick and approachable.
- Custom categories help organize spending around your personal habits.
- Budget limits provide useful alerts before you overspend.
- Clear summaries make it easier to review monthly financial progress.
- Suitable for users who want a lightweight budgeting tool.
Cons
- May lack advanced investment and debt-tracking features.
- Manual entry can become time-consuming for frequent transactions.
- Limited automation may require more regular maintenance.
- Some financial insights may feel basic for experienced budgeters.
- Data backup and synchronization options may depend on the plan.
 Analysis by All-app
Managing a monthly budget sounds simple until everyday spending starts arriving from several directions at once. I found EasyBudget most useful when I treated it as a quick decision-making tool rather than a complete financial command center. It is a free finance app from Wallet Passes Alliance, designed for people who want a clearer view of what they can spend during the month without building a complicated spreadsheet.
That focus is both its appeal and its boundary. The app is approachable enough for a first budget, and its current version, 4.1.0, keeps the experience centered on the basic work of planning and checking a monthly limit. It has reached more than 500 thousand installs, with a 4.0 average from roughly 21 thousand ratings, so it is clearly being used as a practical everyday budgeting option rather than a niche financial experiment.
How EasyBudget fits into a real month
My preferred way to use it is at the beginning of the month, before routine purchases blur together. I enter the amount I can reasonably work with, account for the obligations I already know about, and then use the remaining figure as a guide for flexible spending. That sequence matters: a budget is more useful when it reflects money that is genuinely available, not simply the balance currently visible in a bank account.
A realistic example is a week in which I need groceries, transport, a phone bill, and a few small household purchases. Instead of asking whether each individual item is affordable, I look at how it affects the month as a whole. EasyBudget works well in that moment because it encourages a single question: if I spend this now, will the rest of the month become uncomfortable?
The strongest part of the experience is its low mental overhead. I do not need to understand accounting terminology to get started, and I would feel comfortable recommending it to someone who has tried spreadsheets but abandoned them after a few days. The simple design is not just cosmetic; it reduces the number of decisions between noticing a purchase and recording its effect on the plan.
That simplicity does require discipline from the user. A budget only stays useful when entries are made consistently. If I postpone several purchases and try to reconstruct them later, the picture becomes less trustworthy. The app can help organize my choices, but it cannot make incomplete information accurate. I get the best results when I record spending close to the moment it happens, especially for small purchases that are easy to forget.
When connectivity becomes part of the routine
The connection question is easy to overlook with a budgeting app. I might open it in a supermarket aisle, on public transport, or while standing in a queue, and those are precisely the places where mobile reception can be inconsistent. EasyBudget feels most dependable when I can reach the app and complete an entry without interruption, but I would not build my financial routine around assuming that every location will behave perfectly.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
For that reason, I keep a simple fallback habit: if I cannot update the budget immediately, I make a short note of the purchase and return to the app when I am in a more reliable setting. This is not as satisfying as recording everything at once, but it prevents a temporary connection problem from turning into a forgotten expense. The important point is to treat delayed entry as a deliberate recovery step, not as permission to ignore the transaction.
Connectivity also affects how I think about timing. If I am preparing a budget before leaving home, I prefer to do the planning while my phone is in a stable environment rather than waiting until I am already shopping. That small change makes the process calmer and reduces the chance that a rushed decision will be made without checking the monthly picture first.
I would not describe the app as a replacement for a bank application. A bank app is better for confirming actual transactions, checking account balances, and reviewing official records. EasyBudget is better suited to the planning layer: deciding what I can afford and watching the effect of spending against a personal target. Using the two for different jobs is more sensible than expecting one to do everything.
Using it on a small phone and in busy situations
On a phone, a budgeting tool has to work when I am distracted. I often use this kind of app with one hand, briefly, and without wanting to navigate through several screens. EasyBudget’s straightforward purpose helps here. It is easier to approach for a quick check than a full financial suite filled with investment, account, or reporting sections that I do not need during a normal shopping trip.
My practical tip is to decide on a small set of spending groups before the month begins. I would not create a separate label for every shop or every minor purchase, because that turns a simple monthly plan into maintenance work. Broad, meaningful groups make the result easier to interpret: essentials, transport, food, household needs, and flexible spending are often more useful than a long list of tiny categories.
A second useful habit is to check the budget before a purchase that is optional, not after it. If I wait until the end of the day, the app becomes a diary of decisions already made. If I check first, it becomes a guardrail. This is where the app’s uncomplicated approach can be more valuable than a feature-heavy alternative: I am less likely to abandon the check because it takes too much effort.
The mobile format is also helpful for people who share responsibility for a household but do not want to maintain a formal accounting system. One person can use the monthly plan as a conversation starter about what remains available. I would still avoid treating one person’s entries as a complete record of shared finances unless everyone agrees on how purchases are recorded. A simple tool can support cooperation, but it cannot resolve unclear responsibilities.
There is a trade-off here for advanced users. Someone who wants detailed historical analysis, automatic transaction imports, investment tracking, or sophisticated household permissions will probably outgrow this approach. A spreadsheet or a more comprehensive finance service may be better when the goal is auditing patterns over a long period rather than staying aware of the current month.
What to do when an entry goes wrong
Budgeting apps are especially sensitive to small mistakes. A duplicated purchase can make the remaining amount look worse than it is, while a missed expense can create false confidence. When I notice an error, I correct it as soon as possible instead of trying to compensate with a random adjustment later. The earlier the correction, the easier it is to understand what changed.
I also recommend keeping a short mental distinction between a planned amount and a completed purchase. If I reserve money for groceries but have not spent it yet, that is not the same as recording a grocery transaction. Mixing those two ideas can make a budget appear more precise than it really is. EasyBudget is most helpful when I use it to represent decisions consistently, not when I enter numbers simply to make the screen look complete.
If the app is unavailable at the moment I need it, I use a temporary note and update the budget in one batch later. I check the date and amount before saving each item, then review the remaining plan rather than assuming the correction worked just because the entry was accepted. This two-step recovery is slightly slower, but it protects against the common problem of fixing one mistake by creating another.
Another recovery technique is to start a new month cleanly instead of carrying confusion forward. If the previous month contains several uncertain entries, I would rather identify the amount I can confidently begin with and keep a note about anything still unresolved. Carrying unexplained differences into every later month makes the app harder to trust and makes financial decisions more emotional than they need to be.
These habits reveal an important limitation: EasyBudget can make a plan visible, but it cannot independently verify whether every number is correct. Users who need automatic reconciliation with financial accounts should look for a different type of product. For someone willing to enter and review information manually, the trade-off is a quieter, more focused experience.
Keeping the experience sensible with limited data
Because this is a finance app, I am careful about what I type into any budgeting tool. I use the minimum information needed to plan my spending and avoid turning a simple monthly guide into a personal archive of sensitive details. The app’s value comes from the amounts and decisions that help me budget; I do not need to add unnecessary descriptions that would make the record more revealing.
I also prefer reviewing entries on a trusted connection rather than hurriedly managing financial information in an unfamiliar public setting. That is less about the app’s features and more about good mobile habits. A budget may not contain account credentials, but it can still reveal routines, obligations, and spending priorities. Treating it with the same care as other personal information is sensible.
The free price makes experimentation easy, which is helpful for someone deciding whether a monthly budget will actually become a habit. There are in-app purchases ranging from $0.99 to $99.99 per item, so I would pay attention to the purchase screen and avoid assuming that every available option belongs to the basic free experience. If I were recommending it to a friend, I would suggest starting with the no-cost workflow and only considering an optional purchase after deciding that the app genuinely fits their routine.
Its Everyone age rating also makes the app approachable for a broad audience, although younger users may still benefit from guidance about needs, wants, and irregular expenses. The tool can show the structure of a plan, but it does not replace the conversation that helps someone understand why a budget has limits in the first place.
One non-obvious advantage of keeping the data set small is that reviewing the month becomes less intimidating. I can focus on the categories that influence my next decision instead of getting lost in a detailed history. The disadvantage is that I lose the depth that would help answer questions such as exactly how a spending pattern changed across many months. This is a conscious trade-off, not a flaw that can be solved by using the app differently.
Who should choose it, and who should pass
I think EasyBudget is a good match for a person who wants a lightweight monthly plan, makes most decisions from a phone, and is willing to enter spending manually. It is especially suitable for a first budget, a short-term effort to control discretionary purchases, or anyone who finds traditional spreadsheets too demanding. Its free entry point makes it easy to test without committing to a paid finance service.
I would also consider it for someone whose main problem is not lack of financial information but lack of attention. If the bank balance is available yet does not answer “what can I safely spend this week?”, a dedicated monthly planning view can provide a useful mental boundary. The app helps turn a vague feeling of caution into a number I can consult before making a choice.
I would skip it if I need automatic bank synchronization, complex recurring-payment management, shared live accounts, tax preparation, investment tools, or detailed long-term reports. In those cases, a spreadsheet with custom formulas or a full-featured personal finance platform will likely justify its extra complexity. I would also skip it if I know I will not record purchases regularly. No budgeting interface can compensate for a routine that is never maintained.
Compared with a paper notebook, EasyBudget is quicker to consult and easier to adjust when a plan changes. Compared with a spreadsheet, it asks less setup from me but gives me less control over structure and analysis. Compared with a bank app, it is more focused on intention than on official transaction history. Those comparisons explain its place clearly: it is the middle ground between a handwritten spending limit and a complete financial dashboard.
My connectivity verdict after using the workflow
Connectivity shapes EasyBudget less through a dramatic feature than through the moments when I need to update it quickly. A stable connection makes the routine feel immediate; an unreliable one encourages delayed entries, and delayed entries are where budgeting habits often weaken. My solution is to plan in dependable settings, keep a simple temporary note when necessary, and review the month after any delayed update.
That makes the app a reasonable choice for people who want a focused budgeting companion rather than an all-in-one financial system. Wallet Passes Alliance has kept the central idea easy to understand, and the 4.1.0 release remains accessible to devices using Android 7.0 or later. I appreciate that I can approach it without first learning a complicated method, but I also accept that its usefulness depends on my consistency and on the limits of a manually maintained plan.
After weighing the convenience against those limitations, I would recommend EasyBudget to anyone who wants a simple monthly spending boundary and is prepared to keep it current. I would not recommend it as the sole record of complicated finances or as a substitute for checking a bank account. Used for its proper role, it gives everyday decisions more structure, stays approachable on a phone, and avoids burying a basic budgeting task beneath features I may never use.
Frequently Asked Questions
What is EasyBudget - Budget planning and who is it for?
EasyBudget - Budget planning is a personal finance app designed to help users organize income, expenses, budgets, and savings goals in one place. It can be useful for individuals, couples, students, and families who want a clearer overview of their spending. The app is best suited to users looking for straightforward budgeting tools rather than advanced investment or accounting software.
How does EasyBudget help me track my spending and manage a budget?
The app allows you to record financial transactions, categorize expenses, and compare your actual spending with the limits you set for different budget categories. By reviewing these entries regularly, you can identify recurring costs, monitor where your money goes, and make adjustments before overspending becomes a problem. Its usefulness depends on entering transactions accurately and consistently.
Does EasyBudget connect to my bank accounts automatically?
Whether automatic bank synchronization is available may depend on the version of EasyBudget, your country, and the platform you use. Some users may need to enter income and expenses manually instead of linking financial accounts. Before downloading, check the app’s current store description and privacy information to confirm supported banks, synchronization features, and whether your financial data is shared with any third-party service.
Is my financial information safe when using EasyBudget?
Before adding sensitive financial details, review EasyBudget’s privacy policy, permissions, and security information in the Google Play Store or Apple App Store. Avoid entering passwords, card PINs, or unnecessary banking credentials unless the app clearly explains why they are required. Using a device lock, keeping the app updated, and backing up data securely can also help protect your budgeting information.
Is EasyBudget free to download, and are there in-app purchases?
EasyBudget may be available as a free download, but certain features can vary depending on the edition, operating system, or subscription plan. Premium tools might include additional categories, reports, synchronization, backups, or an ad-free experience. Check the current store listing for pricing, trial terms, and recurring charges before confirming a purchase, especially if you are using a shared family payment account.